Get a Quote

Lending

Using Evaluations Across the Loan Lifecycle

Origination, renewal, credit review, portfolio monitoring, and disposition all benefit from consistent collateral insight.

Read the insight

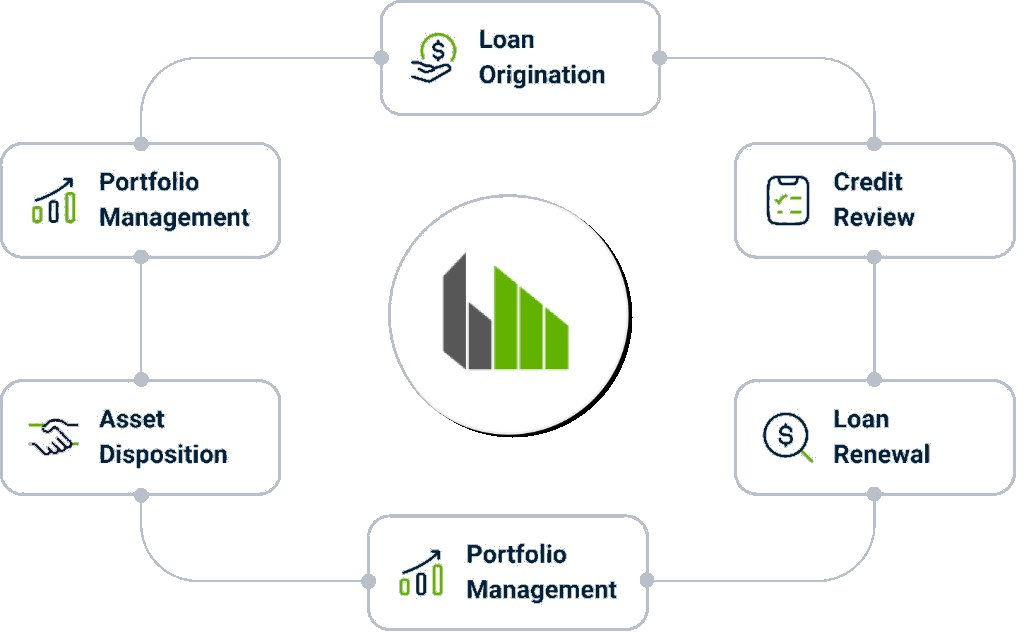
The credit cycle

Using Evaluations Across the Loan Lifecycle
Evaluations can support origination, review, renewal, portfolio management, and disposition when policy allows.

A single evaluation product can support multiple credit events when scoped to the institution’s policy. Origination files, renewals, credit reviews, and portfolio monitoring all need a current view of the collateral — but they do not always need a full appraisal.

Credit teams typically return to the same questions: is the property as represented, does the market still support the income story, and is the value indication still useful for the decision at hand.

Where it shows up

Where evaluations typically enter the file.

01

Loan origination

A FIRREA-aligned opinion of value when loan size and policy allow an evaluation instead of an appraisal.

02

Credit review

A refresh when occupancy, lease status, or local pricing has moved since closing.

03

Loan renewal

Updated collateral support before extending term or changing structure.

04

Portfolio management

A consistent format that risk and credit can compare across small-balance CRE.

05

Asset disposition

A documented basis for workout, sale, or refinance conversations.

The product still has to match the institution’s policy, the collateral, and the credit event. The value of using one evaluation framework across the lifecycle is that reviewers see the same evidence structure each time, rather than a new template for every request.

Keep reading

One framework, many credit events.

When the evaluation format stays consistent, credit, risk, and reviewers spend less time relearning the file — and more time judging the collateral.

Back to Insights Explore commercial evaluations